Every six months the same list resurfaces: translators, journalists, customer service agents, lawyers, accountants, junior developers. It is presented as the verdict of the “most recent studies”. Those studies exist, they are serious, and they are being cited wrongly.
The problem is not exaggeration. It is more precise than that: this body of work measures exposure — the share of an occupation’s tasks that a language model could take on. It does not measure jobs destroyed. Their authors say so in black and white.
Yet for the past year there have been data series that count real jobs. They tell a different story, narrower and far more worrying than the list of doomed occupations — because the effect they measure is almost invisible today, and arithmetically impossible to undo tomorrow.
What the “jobs at risk” rankings measure, and what they do not
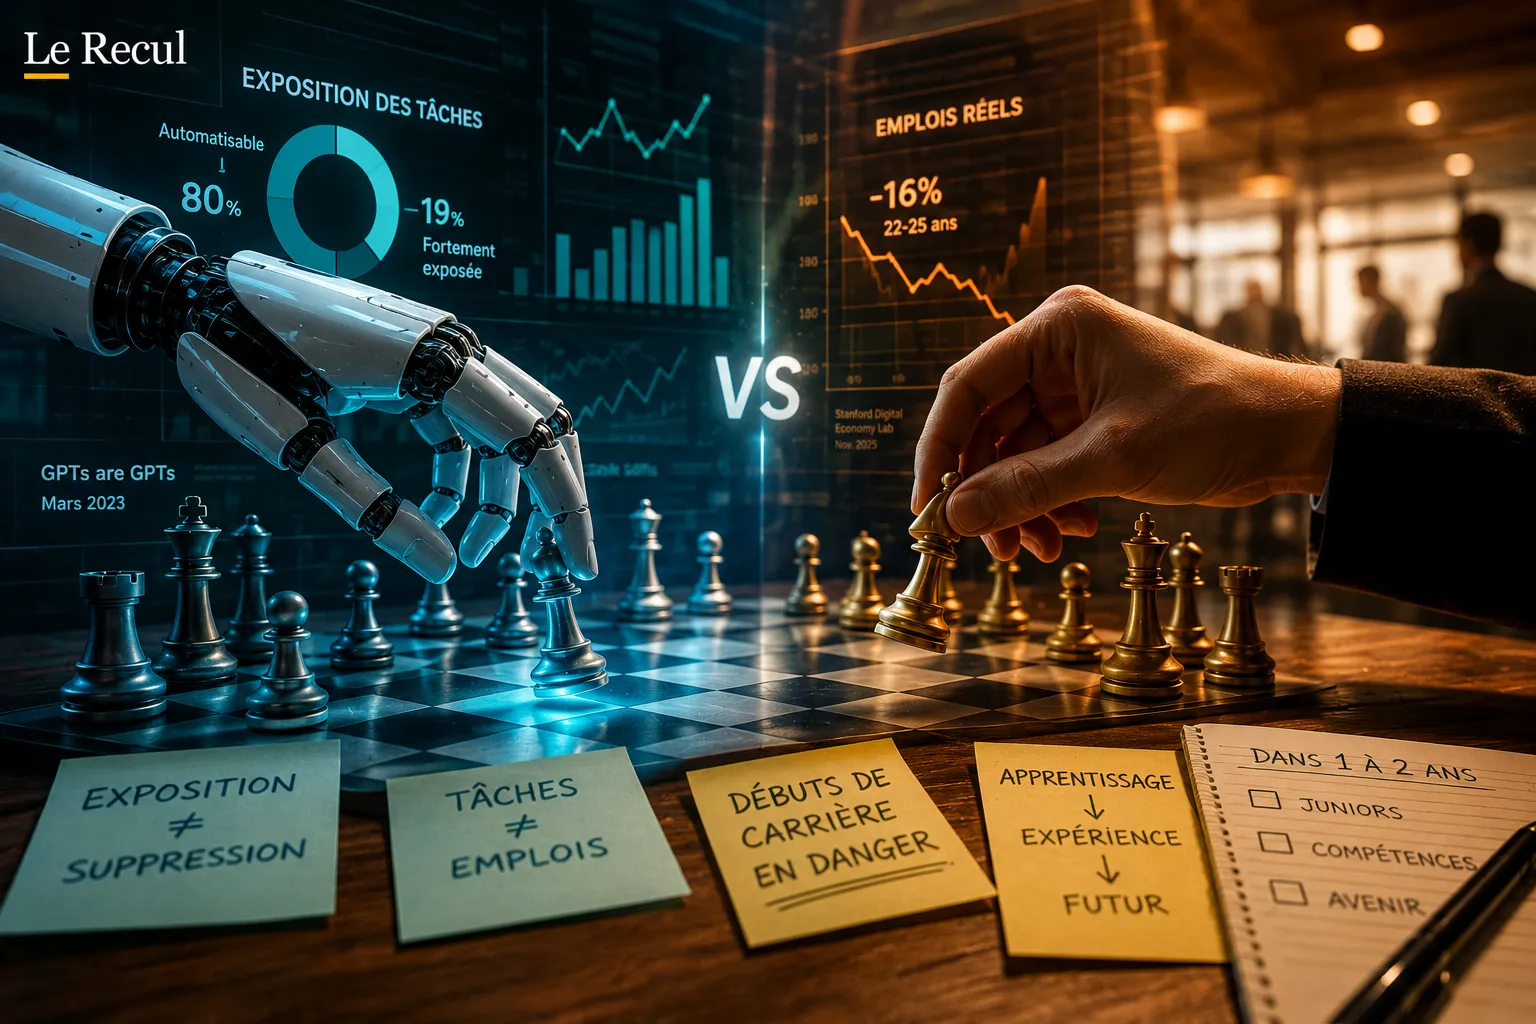
The founding study is called GPTs are GPTs. Published in March 2023 by Tyna Eloundou, Sam Manning and Pamela Mishkin (OpenAI) with Daniel Rock (University of Pennsylvania), it establishes that around 80% of American workers could see at least 10% of their tasks affected, and 19% at least half. Those are the two figures that have fed almost every list for three years.
“Affected” means neither destroyed nor degraded. The paper assesses whether a model can cut the time a task takes by at least half, at constant quality. A task that gets faster can remove a post; it can also free the person doing it for something else, or push the price of the service down far enough to increase demand. Nothing in the method settles the question.
The ranking most widely repeated today comes from Microsoft Research (Working with AI, July 2025), built from 200,000 real conversations with Copilot. It gives each occupation an “applicability score”. At the top: interpreters and translators, at 0.49, with task coverage of 0.98. Then historians, services sales representatives, writers, customer service representatives, telephone operators and journalists.
That list travels everywhere. The sentence that accompanies it in the paper, much less so: a high applicability score does not mean an occupation will be eliminated, and the data does not show that an AI can perform any one of these professions in full.
The real age of the “most recent studies”
This is the simplest check, and the one most rarely run.
| Source | Actual date | What it measures |
|---|---|---|
| OpenAI / U. Pennsylvania | March 2023 | Theoretical task exposure, before GPT-4 had even reached the public |
| OECD, Employment Outlook | 2023 (2022 survey) | Perceptions of finance and manufacturing employees, seven countries |
| IMF, "40% of jobs" | 14 January 2024 | Jobs "affected", half of them positively according to the IMF itself |
| Microsoft Research | July 2025 | Applicability observed in Copilot conversations |
| Gartner, "500 million jobs" | 20 October 2025 | Jobs net created by 2036 — often cited as 2033 |
Two distortions come back every time. The IMF figure is truncated: the January 2024 report speaks of 40% of jobs worldwide and 60% in advanced economies, but Kristalina Georgieva immediately added that around half of those exposed jobs could benefit from AI through productivity gains. As for the Gartner forecast, it is cited with the wrong date and back to front: it concerns more than 500 million net new jobs created to support AI deployments, by 2036.
Not one of these sources was designed to answer the question “is my job going to disappear”. All of them are used for it.
The only data that counts real jobs
One team counts real wages, every month, on administrative records: Erik Brynjolfsson, Bharat Chandar and Ruyu Chen, at the Stanford Digital Economy Lab. Their paper Canaries in the Coal Mine? draws on the payroll files of the largest American payroll provider. No employer statements, no projections.
In the version of 13 November 2025, the central result is a relative fall in employment of 16% among 22-25 year olds in the occupations most exposed to generative AI, once firm-level shocks have been netted out. The first version, in August 2025, measured 13%: the effect has strengthened, not faded.
Three elements of this work matter more than the headline figure.
Employment among experienced workers in the same occupation does not move. So it is not the occupation that is receding. It is one age group inside the occupation.
The adjustment runs through employment, not through pay. Firms have not cut wages: they have stopped opening posts. The mechanism is not redundancy, it is the end of hiring. A young worker does not lose the job — they never find it. That is precisely why the phenomenon produces no redundancy plan, no industrial dispute and no visible statistic.
The fall is concentrated where AI automates rather than assists. Junior developers and customer service agents fall into the first case. Care assistants, by contrast, are seeing their employment grow faster among the young than among their seniors.
The counterpoint: at national level, nothing is visible
This result has to be read alongside its contradictor, on pain of alarmism. The Budget Lab at Yale tracks the same questions on American labour force survey data and concludes that no broad disruption is measurable since ChatGPT was released: the distribution of workers across highly, moderately and lightly exposed occupations has stayed stable, and the unemployed show no over-exposure to AI. Yale notes a “low-flow” market in early 2026 — few redundancies, few hires — without attributing it to AI.
Official projections point the same tempered way. The American Bureau of Labor Statistics projects a 5% decline between 2024 and 2034 for customer service representatives, explicitly citing automation — but 341,700 openings a year over the decade, with retirements and occupational switching dominating the technological effect by a wide margin. For paralegals, the projection is near-stability, with growth “limited by technological advances, including artificial intelligence”.
These two readings do not contradict each other. They complete each other: nothing visible at macroeconomic scale, a sharp and localised effect on one specific population. That is exactly the signature of a phenomenon at the start of its course — and it is also what makes it easy to ignore.
The one occupation where the effect really is quantified
Translation is the textbook case, and the only one where an elasticity has been estimated. The available work associates each additional percentage point of machine translation use with a slowdown of around 0.7 point in the growth of translator employment, in the order of 28,000 posts not created between 2010 and 2023.
The important phrase is “not created”. These are not redundancies, and the global translation market has not collapsed. What has shifted is value: it is concentrating on the segments that carry real liability — legal, medical, financial — and on revising machine output. European professional surveys indicate that a large majority of translators see AI as a threat, and that a third say they have already lost contracts.
In other words, the occupation that has topped every exposure ranking since 2023 has not disappeared in three years. It has closed from the bottom.
What firms announce, and what the volume says
In the United States, AI has become the most cited reason in job-cut announcements, for four consecutive months through June 2026, according to Challenger, Gray & Christmas. In June, out of 45,849 announced cuts, 14,029 were attributed to AI, or 31%. Across the first half, the running total reaches 101,743 AI-related cuts — around 23% of all cuts — and 173,568 since 2023.
Context is indispensable. Total announced cuts in the first half of 2026 come to 443,604, down 40% year on year (744,308 in the first half of 2025). AI’s share is therefore growing inside a volume that is shrinking. The technology sector alone accounts for 139,156 cuts, up 83%.
Above all, this is a reason declared by the employer, not an established cause. We have documented elsewhere why that reason is convenient — between restructurings inherited from post-Covid over-hiring and a warm reception from financial markets: that is the subject of our analysis of the reversal behind layoffs “because of AI”.
In France: the same signal, measured on job adverts
On 13 May 2026, INSEE published the first-quarter figures: overall unemployment at 8.1%, up 0.2 point. Among 15-24 year olds, 21.1% — down 0.4 point over the quarter, but up 2.0 points year on year. None of those moves is attributed to AI by INSEE, and it would be dishonest to do it on their behalf: the business cycle, the cost of apprenticeships and the decline of work-study contracts all weigh heavily.
The most useful French work is by Philippe Aghion, Antonin Bergeaud, Simon Bunel and Paul Delbouve, published in July 2025 from more than 120 million job adverts posted in France since 2019. Its result works on two levels: the firms most exposed to AI have been hiring markedly more specialists since ChatGPT arrived, their productivity and revenue are rising, and their total employment is growing — but with a relative decline in job creation in the most exposed occupations, in favour of the less exposed ones. Diffusion remains highly concentrated: IT, finance, consulting, large pioneering firms, and employment areas hosting research clusters.
A quieter complementary signal comes from the requirements set out in the adverts themselves: according to PwC work relayed in France, postings aimed at juniors are flat in heavily exposed sectors, while adverts for equivalent roles asking for an intermediate or senior level have risen sharply since 2019. The post is not disappearing: its entry ticket is going up.
The jobs least at risk, and the ones nobody can fill
The France Travail labour needs survey counts 2.28 million hiring plans for 2026, of which 43.8% are judged difficult. The highest difficulty rates sketch a list that AI exposure rankings never intersect: roofers and waterproofing specialists above 80%, bricklayers and formworkers above 78%, plumbers and heating engineers above 75%, home and residential care assistants above 72%, lorry drivers above 70%, nurses above 68%.
These occupations share one simple property: physical presence, engaged liability, non-standardised environments. That is exactly what current systems cannot do — to the point that some platforms have started renting out humans to carry out the physical tasks AI cannot perform.
The real criterion is not the occupation, it is the task
This is the conclusion common to all this work, and it invalidates the very logic of ranking by profession.
The Anthropic Economic Index published on 24 March 2026, built on real Claude usage in February 2026, estimates that 49% of occupations have had at least a quarter of their tasks performed through the model, with computing and mathematics occupations alone accounting for 35% of conversations. Almost every occupation is therefore affected somewhere — which mechanically strips any discriminating value from a list of “occupations concerned”.
The useful question lies elsewhere: in your work, does AI carry out a task from start to finish, or does it assist with a task you remain responsible for? The first case removes billable hours; the second shifts the content of the post. We have watched that switch happen among developers, some of whom are already sliding into a supervisor’s role, and in the tools that are moving beyond code to take on whole office tasks.
One year out (2027): the “junior” threshold rises
To look ahead you need an indicator that measures what systems can really do, not what their makers announce. The most honest one available comes from METR, an independent evaluation lab: the length of a task a model can complete alone with a 50% success rate. In version 1.1, published on 29 January 2026, on a suite extended to 228 tasks, that horizon reaches around 320 minutes for the best model evaluated, more than five hours. The doubling time is 196 days across the whole period, but 89 days if you keep only the data since 2024.
METR attaches explicit caveats to those figures, and they bear repeating: the confidence intervals remain very wide, only 5 of the 31 long tasks have a genuinely measured human completion time, and the trend is sensitive to the composition of the suite.
What is well supported. If the trend holds, even on the low assumption of seven months, the autonomous task horizon moves from half a day to roughly a full working day during 2027. And a framed, repeatable, checkable working day is very precisely the definition of a junior post. The pressure will not fall on “translators” or “lawyers”: it will fall on the first rung of those occupations, as it already does.
What is plausible but uncertain. An extension of the phenomenon beyond tech and customer service, towards administrative functions, first-line accounting and standardised content production. The tipping point will depend less on technical capability than on trust: an agent that fails half the time on five hours of work replaces nobody without supervision — and that supervision costs senior time.
What is speculation. The disappearance of an identifiable occupation, a measurable rise in overall unemployment attributable to AI, or the opposite — a wave of net job creation visible as early as 2027. At one year out, none of those three hypotheses is supported.
Two years out (2028): the year the bill arrives
2028 is the deadline lab executives set themselves, and above all it is the moment when the spending will have to meet a revenue. It is also the year two contradictory effects reach maturity at the same time.
On one side, the substitution machine keeps running. If agentic deployments deliver on their promises, intermediate execution roles — the ones that today take two to five years of experience — become exposed in turn. Agents that act alone on real systems and assistants installed permanently in the working environment are no longer demonstrations: they are being generalised.
On the other, the backlash arrives. Firms that stopped hiring juniors in 2024, 2025 and 2026 will have, by 2028, a three- or four-cohort hole in their intermediate ranks. That is not a technology prediction, it is cohort arithmetic: a senior professional of 2032 is a junior hired in 2026. No technology compresses years of experience, and no budget buys back a skill that was never passed on.
What is well supported for 2028. The divergence persists between the stock of jobs — stable — and the inflow — degraded. It is the only mechanism three independent sources already measure.
What is plausible but uncertain. A market correction: if half of corporate AI projects keep producing no measurable return, part of the cuts justified by AI will be quietly rehired, as has already begun. A reverse tension on intermediate profiles is equally credible, with wage inflation on the few available seniors.
What is speculation. Public policy that would rebuild the entry rung — conditional apprenticeship quotas, training obligations, targeted tax incentives. Nothing of the kind is on the table today in France, or elsewhere in Europe. For a longer view, we have published a separate projection at one, two and five years across the sector as a whole.
The risk nobody really talks about
Let us restate the full mechanism, because it is counter-intuitive and that is what makes it dangerous.
AI does not remove occupations: it removes learning tasks. Proofreading a standard contract, fixing a simple bug, handling a routine customer request, translating a low-stakes document, producing a first draft — these are low value-added tasks for the employer, and very high value tasks for whoever carries them out. They were the school of the trade. They are exactly the ones a model performs correctly today.
A rational firm automates them. Each decision, taken in isolation, is justified. The aggregate is not: the sector stops manufacturing the professionals it will need, and the cost appears on no balance sheet for several years.
That is what distinguishes this phenomenon from a classic wave of automation. A machine tool that replaces a worker produces an immediate, visible, measurable, negotiable conflict. A junior post that is never opened produces nothing at all: no redundancy, no statistic, no counterparty. The cost is real, but it is deferred — and it is paid by people who have no say in it, because they are not yet anybody’s employees.
What this changes in practice
If you have been in post for several years, no available data documents a specific risk tied to your occupation. The measured signal does not concern you — it concerns the posts your employer will not open, and in time the supervision load that will fall to you.
If you are entering the market, the risk is real and it is about access, not competence. Occupations where AI carries out complete tasks offer fewer junior posts, even though those posts remain the only route to the experience you will be asked for three years later. The strategy that follows from the data: aim for roles where AI assists without executing, and for environments where liability stays human.
If you are hiring, using an AI system to screen applications, select candidates or decide on a promotion falls under high-risk systems within the meaning of the European regulation, with the corresponding documentation and human oversight obligations — a timetable whose successive adjustments we have set out.
If someone is selling you a course to “escape the jobs at risk from AI”, ask what data the list rests on. In most cases the answer goes back to a theoretical exposure table from 2023. We have tested what those offers are worth in our investigations into income promises built on AI and into courses costing nearly €2,000.
Finally, if you want to follow what models can really do rather than what is announced, our AI ranking is updated continuously, with dedicated views for coding agents and for cost against performance — the two dimensions that decide, in practice, what a company automates.
What Le Recul takes from this
Lists of jobs at risk are not false: they answer a different question from the one put to them. They rank task exposure, measured in 2023, 2024 and 2025, not jobs lost.
The real employment data converges on a narrower and more precise phenomenon. At the scale of the economy, nothing visible — that is Yale’s conclusion, and the World Economic Forum even expects a net positive balance of 78 million jobs by 2030. At the scale of one age group, a clear and documented fall: 16% among 22-25 year olds in the most exposed occupations, with no movement among their experienced colleagues, and through a hiring freeze rather than through redundancies. In France, the same signal shows up in job adverts, with no fall in total employment.
The risk documented in 2026 is therefore not about occupations, but about career starts — and by ricochet, three or four years out, about the availability of the senior professionals those starts would have produced. That is a different problem, with different answers, and it stays badly posed for as long as we keep treating it as a list of condemned professions.
The right question is not “is my job on the list?”. It is: “in my line of work, who will still learn the trade in five years?”
The figure to keep
16%. That is the relative fall in employment among 22-25 year olds in the occupations most exposed to generative AI, measured on American payroll data by the Stanford Digital Economy Lab. Over the same period, in the same occupations, employment among experienced workers stayed flat — and it is that stability, more than the fall, that shows where the problem really sits.